Embezzlement and money laundering are two distinct financial crimes that are often conflated, despite their divergent nature and execution. Two of the most commonly used terms for criminal activities are embezzlement and money laundering, but what differentiates these two activities? In this post, we will clarify their key differences, legal risks, real-world cases, and more.
What Is Embezzlement and How Does It Work?
Embezzlement occurs when a person takes or misuses assets or funds that have been entrusted to them for personal gain. This means that it must be conducted by a person with legitimate access such as employees, fiduciaries, and managers.
Examples of Embezzlement
The types of organizations in which embezzlement can occur are very numerous, ranging from small businesses to multinational corporations.
Some common examples include:
- Employees who have access to financial systems or funds divert corporate funds into a personal bank account,
- Financial advisors misusing their clients’ funds for personal gain,
- Fiduciaries manipulating records or systems through fake refunds, shell companies, or fraudulent invoices.
What Is Money Laundering and Why Is It a Global Risk?
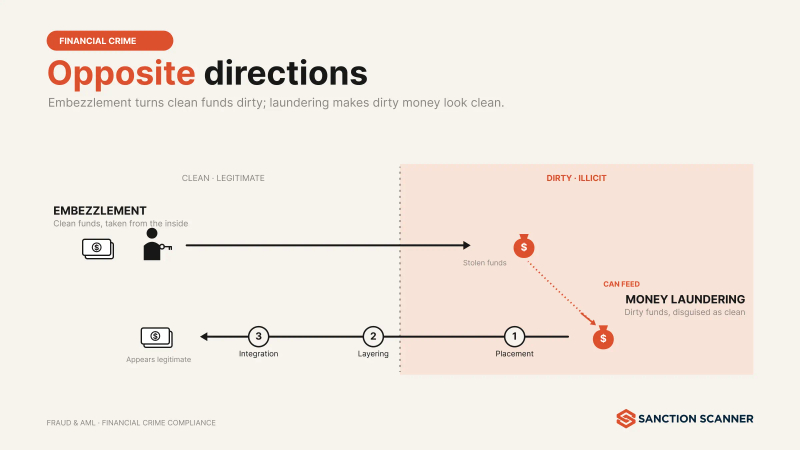
Money laundering refers to the act of disguising the origins of funds obtained through illicit activities such as drug trafficking, fraud, or human trafficking in order to make them appear legitimate.
There are typically three main stages of money laundering: Placement, layering, and integration.
Placement: In the first stage, illegally obtained funds are introduced into the financial system often by splitting large amounts of cash into smaller sums to deposit into a bank account, or purchasing monetary instruments such as checks or money orders. Other notable methods are: adding illicit cash to the legitimate resources of a business, false invoicing, smurfing (inserting small amounts of money below the reporting threshold), and hiding the beneficial owner’s identity.
Layering: Then, criminals conduct a series of financial transactions to obscure the source of funds. The funds may be channeled through the purchase and sale of investments, holding companies, or simply moved through a series of accounts at banks around the globe. Some examples of layering tactics are multiple international transfers, use of shell companies, frequent account hopping, converting to and from cryptocurrencies, chain-hopping, investments in complex financial instruments, and structuring large transfers.
Integration: As the last step, integration refers to reintroducing illicit funds into the financial system. Criminals often invest in real estate, luxury assets, or business ventures. There are several integration tactics that can be mentioned such as fake employees, loans to directors or shareholders, or dividends paid to shareholders of companies controlled by criminals.
How Does Embezzlement Differ from Money Laundering?
Embezzlement and money laundering differ in where the money comes from and what the offender does with it. An embezzler obtains lawful access to the funds and then misuses them with intent, so the crime is the taking itself. Money laundering, by contrast, begins with funds that were obtained unlawfully and consists of disguising their origin so they can be used freely.
|
Embezzlement |
Money laundering |
|
|
Origin of funds |
Legitimate funds belonging to an employer, client or beneficiary |
Proceeds of a prior crime (drugs, fraud, corruption, trafficking) |
|
Who commits it |
An insider with entrusted access: Employee, manager, fiduciary, adviser |
The original criminal (self-laundering) or a third party acting for them |
|
Type of access |
Lawful access, unlawful use |
No lawful claim to the funds at any point |
|
Required intent |
Intent to permanently deprive the owner or misuse the assets |
Knowledge or suspicion that the funds are criminal proceeds, and intent to conceal |
|
Stage of the crime |
The predicate offence itself |
A downstream offence that follows a predicate crime |
|
Typical predicate offence |
None; embezzlement is the source crime |
Drug trafficking, fraud, corruption, tax evasion, embezzlement |
|
Key red flag |
Missing funds, altered records, payments to unknown vendors |
Structured deposits, rapid pass-through transfers, shell company layers |
|
Investigating body |
Internal audit, forensic accountants, police or prosecutors |
Financial intelligence units, law enforcement, banks via SAR/STR filings |
|
Typical penalty |
Theft or fraud statutes; up to 10 years in the UK (Fraud Act 2006), up to 30 years for bank embezzlement in the US |
Up to 20 years in the US (18 U.S.C. 1956), up to 14 years in the UK (POCA 2002) |
Can Embezzlement Lead to Money Laundering?
Yes. Embezzlement is a predicate offence for money laundering, which means that once the funds are taken, any step the offender takes to disguise them is a second, separate crime. To avoid detection, embezzlers move stolen funds through multiple accounts, route them through shell companies, invest them or purchase high-value assets such as property and vehicles.
The legal hinge here is the distinction between self-laundering and third-party laundering. Self-laundering is when the person who committed the predicate offence launders their own proceeds. It is a criminal offence in the United States, in the United Kingdom under the Proceeds of Crime Act 2002, and across the EU since Directive (EU) 2018/1673 required member states to criminalise it. Third-party laundering is when someone else, often a professional launderer, handles the proceeds for a fee. In practice, an embezzler who wires stolen funds to a relative's account and then buys a car with them can be charged with both embezzlement and money laundering, and the laundering count frequently carries the longer sentence.
What Are the Red Flags?
|
Embezzlement red flags |
Money laundering red flags |
|
Missing funds and altered records of invoices, receipts, or financial statements |
Several small transactions just below regulatory reporting thresholds, a practice known as structuring |
|
Staff living above their means, not taking vacations, and extreme secrecy about financial matters |
Frequent international transfers, especially with jurisdictions known for weak oversight |
|
Payments to unknown vendors and repeated payments just under reporting thresholds |
Complex and unnecessary transaction chains involving no clear business purpose, shell companies, and high-value asset purchases |
High-risk jurisdictions in the second column are those on the FATF grey and black lists.
Which Industries Are Most at Risk?
Both crimes cluster in sectors where money moves in volume, oversight is thin or trust replaces controls. The table below shows which crime each sector is most exposed to and why.
|
Sector |
Exposed to |
Risk driver |
|
Finance and banking |
Both |
Employees with direct access to client funds; high transaction volume that hides laundering |
|
Public sector |
Embezzlement |
Weak oversight in some agencies; single officials controlling budgets |
|
Non-profits and charities |
Both |
Heavy reliance on trust; volunteer-run finance; cross-border donations |
|
Healthcare |
Embezzlement |
Complex billing systems; fake refunds and vendor invoices are easy to hide |
|
Real estate |
Both |
Large single transactions; layered ownership; escrow accounts held by insiders |
|
Retail and hospitality |
Both |
Cash-heavy environments; skimming at the till; illicit cash mixed with takings |
|
Casinos and gambling |
Money laundering |
Chips and winnings convert cash into clean payouts |
|
Luxury goods |
Money laundering |
High-value assets that store and move value with little scrutiny |
|
Cryptocurrency |
Money laundering |
Cross-border transfers, chain-hopping and weak KYC at some exchanges |
|
Import-export |
Money laundering |
Trade-based laundering through over- and under-invoicing |
|
Professional services |
Money laundering |
Lawyers and accountants used to set up complex ownership structures |
How Are These Crimes Investigated?
|
How embezzlement is investigated |
How money laundering is investigated |
|
Specialists analyze financial records, transactions, invoices, and ledgers to find anomalies, unexplained transfers, and patterns of misappropriation that may indicate fraud |
Law enforcement agencies and financial intelligence units (FIUs) analyze financial transactions and Suspicious Activity Reports (SARs) to identify patterns that may indicate money laundering or linked criminal activities |
|
Interviews and audits with employees, witnesses, and suspects to collect statements |
Investigators use data analytics, artificial intelligence, software tools, and pattern detection to trace funds across accounts and jurisdictions |
|
Investigators obtain legal authority to search premises, seize documents, or issue subpoenas to build a case |
Shared intelligence and coordinated investigations by agencies like INTERPOL, FATF, and national FIUs for cross-border operations |
Well-managed Suspicious Activity Reports are the raw material of most laundering investigations; the FATF sets the standards that national FIUs apply.
What Are the Penalties?
As expected, the penalties differ considerably depending on the jurisdiction and the amount of misused money. However, offenders typically face prison sentences, heavy fines, and mandatory restitution or asset confiscation. The table below sets out the statutory maximums in the three jurisdictions most relevant to our readers.
|
Jurisdiction |
Offence |
Maximum sentence |
Fine |
Statute |
|
United States |
Money laundering |
20 years per count |
Up to $500,000 or twice the value of the property involved, whichever is greater |
18 U.S.C. § 1956 |
|
United States |
Embezzlement (bank officer or employee) |
30 years |
Up to $1,000,000 |
18 U.S.C. § 656 |
|
United States |
Embezzlement of public money or property |
10 years |
Per the federal fine schedule (up to $250,000 for individuals) |
18 U.S.C. § 641 |
|
United Kingdom |
Money laundering |
14 years |
Unlimited |
Proceeds of Crime Act 2002, ss. 327 to 329 |
|
United Kingdom |
Embezzlement (prosecuted as theft or fraud by abuse of position) |
7 years (theft), 10 years (fraud by abuse of position) |
Unlimited |
Theft Act 1968, s. 1; Fraud Act 2006, s. 4 |
|
European Union |
Money laundering |
At least 4 years (minimum maximum that member states must provide) |
Set nationally |
Directive (EU) 2018/1673, Art. 5 |
|
European Union |
Misappropriation affecting EU funds |
At least 4 years for serious cases (minimum maximum) |
Set nationally |
Directive (EU) 2017/1371 (PIF Directive), Arts. 4 and 7 |
In the EU, embezzlement in the private sector is not harmonised and is prosecuted under national law, for example as Untreue under section 266 of the German Criminal Code (up to five years, ten in serious cases). Across all three jurisdictions, confiscation of the proceeds and restitution to the victim sit on top of the prison sentence.
What Are Some Notable Real-World Cases?
In this section we look at four cases, two of embezzlement and two of money laundering, and what each one cost.
Embezzlement cases
Rita Crundwell, City of Dixon: Over roughly two decades, the comptroller of Dixon, Illinois, a town of about 16,000 people, diverted around $53.7 million of city funds into a secret account she controlled and spent it on a horse-breeding operation and a luxury lifestyle. She was arrested in 2012 after a colleague covering her leave noticed the account, and in 2013 she was sentenced to 19 years and 7 months in federal prison. It remains the largest municipal embezzlement case in US history, and it happened in a finance office where one person opened the mail, paid the bills and reconciled the books.
Tyco Case: According to the Guardian, former Tyco chiefs Dennis Kozlowski and Mark Swartz were sentenced to between 8 and 25 years in prison and ordered to pay a total of $134M in restitution back in 2005. Prosecutors stated that Mr. Kozlowski used company money to pay for a $2M birthday party for his wife, an $18M New York apartment, and gifts for a former marketing manager with whom he was having an affair.
Money laundering cases
Danske Bank Scandal: According to Reuters, around $227B in payments flowed through the non-resident portfolio of Danske Bank’s Estonian branch between 2007 and 2015 due to inadequate anti-money laundering controls of the bank. A huge portion of this money was money-laundered cash flowing illegally out of Russia, the UK, and the British Virgin Islands. In December 2022, Danske Bank pled guilty and agreed to a $2 billion fine. However, the repercussions weren’t limited to this: Ten former employees of the bank were arrested, the Estonian branch was closed, the CEO Thomas Borgen resigned, and the value of Danske Bank shares was halved.
HSBC Scandal: According to BBC, in 2012, the U.S. authorities revealed that the bank had failed to implement adequate controls to detect transactions worth billions of dollars linked to drug cartels, terrorist organizations, and sanctioned countries. Furthermore, investigations showed that HSBC ignored warning signs and maintained weak monitoring systems. In the end, HSBC agreed to pay a record $1.9B settlement to the U.S. authorities.
How Can Businesses Prevent These Crimes?
Strong Internal Controls and Compliance Systems: One of the most important things that a business can do is to implement segregation of duties, which means no single person can initiate or approve a transaction alone. This is particularly important for addressing internal theft such as embezzlement.
Regular Internal and External Audits: Audits are incredibly helpful when it comes to identifying weaknesses early and reinforcing accountability. Allowing independent reviews of accounts and transactions makes it much more efficient to catch the misuse of funds.
Anti-Money Laundering Programs: Today, these programs are not a prerequisite only for financial services, various businesses in other sectors, as we have mentioned in the previous parts, must also implement AML programs including Know Your Customer (KYC), Ongoing Monitoring, Customer Due Diligence (CDD), and more.
A Culture of Ethical Behavior: Regular training sessions, clear policies, and whistleblower channels encourage employees to report suspicious activity and understand consequences more clearly.
Converged Fraud and AML Operations: Because embezzlement is a predicate offence for laundering, the two control functions see the same case from different ends. Businesses that run them as one operation catch more: Use a single transaction monitoring program that combines AML rules with internal fraud scenarios, cross-train staff across the anti-money laundering and anti-fraud teams so each understands the other's policies, establish one alert remediation process with shared standards for closing cases, and run both functions on a single case management system so investigators can exchange files instead of duplicating work.
What Tools Help Detect and Prevent These Crimes?
Automated Monitoring and Analytics Software: Tools such as transaction monitoring, anomaly detection, and pattern recognition help flag unusual activity that could indicate embezzlement or laundering.
For example, Sanction Scanner’s transaction screening software screens customer transactions and stops the transactions and records them for investigation if it detects a suspicious transaction, which helps reduce false positives by up to 97% and reduce workload by up to 80%.
Forensics: Forensic software allows businesses to trace fund flows, reconstruct transaction histories, and uncover any kind of manipulation of records that may signal embezzlement or money laundering.
Name Screening, Know Your Customer (KYC) and Customer Due Diligence (CDD): These verify the identity of clients, assess risk profiles, and screen them against sanctions lists and politically exposed person (PEP) lists. Therefore, the risk of onboarding individuals or entities linked to criminal activity is reduced.
For example, Sanction Scanner’s modules allow the screening of customers and businesses against more than 3,000 data points consisting of global sanctions lists, PEP lists, and adverse media data from more than 220 countries and territories.
Conclusion
Embezzlement is a crime of trust: Someone with lawful access takes what was entrusted to them. Money laundering is a crime of concealment: Someone with unlawful proceeds makes them look legitimate. The two meet whenever an embezzler tries to hide what they took, which is why internal controls and AML programs are strongest when they share data and a case queue. If you are reviewing your own exposure, start with the red flags and sector table above, check that no single person can both initiate and approve a payment, and make sure your transaction monitoring rules cover insider patterns as well as external laundering typologies.
FAQ's Blog Post
The fastest single control is segregation of duties combined with a converged fraud and AML monitoring program. No individual should be able to initiate, approve and reconcile a payment alone, and internal fraud scenarios should run on the same transaction monitoring system as AML rules. Businesses that keep the two functions separate typically discover an embezzlement only after the laundering stage has begun.
Finance, public sector, non-profits, healthcare, real estate, retail and hospitality carry the highest embezzlement risk because insiders have direct access to funds, oversight is thin or the environment is cash-heavy. Money laundering risk concentrates in casinos, luxury goods, cryptocurrency, import-export and professional services, where large cross-border flows and complex ownership structures make concealment easier.
Embezzlement red flags are internal: Missing funds, altered invoices, payments to unknown vendors and staff who never take leave. Money laundering red flags are transactional: Structured deposits below reporting thresholds, rapid international transfers to weak-oversight jurisdictions and layered shell company chains. A monitoring program that only watches one set misses the point where an embezzler starts laundering.
A company is normally the victim of embezzlement, but it can face liability if the stolen funds belonged to clients and its controls were negligent. Regulators and courts look at segregation of duties, audit frequency and whether one person could both initiate and approve payments. The Dixon case, where one comptroller controlled every step for two decades, shows what weak controls cost.
The Madoff case was a Ponzi scheme, a form of investment fraud in which new investors' money paid earlier investors' returns. Madoff was convicted in 2009 on eleven counts including securities fraud and money laundering and sentenced to 150 years. Calling it embezzlement is a common error: The funds were obtained by fraud, not misappropriated from lawful custody.
Self-laundering is when the person who committed the predicate crime launders their own proceeds. It is criminalised in the United States, in the United Kingdom under POCA 2002 sections 327 to 329, and across the EU since Directive (EU) 2018/1673. An embezzler who moves stolen funds through a relative's account can therefore be charged twice, and the laundering count often carries the longer sentence.
Money laundering usually carries the higher statutory maximum: 20 years per count in the United States under 18 U.S.C. § 1956 and 14 years in the United Kingdom under the Proceeds of Crime Act 2002. Embezzlement is charged as theft or fraud, with maximums of 7 to 10 years in the UK, though US bank embezzlement under 18 U.S.C. § 656 reaches 30 years.
Embezzlement is not a form of money laundering; it is a predicate offence that can lead to it. Embezzlement is the taking of entrusted funds, while laundering is the concealment of criminal proceeds afterwards. Under Directive (EU) 2018/1673 and 18 U.S.C. § 1956, an embezzler who disguises the stolen money commits a second, separately punishable crime.